More sportsbook accounts create flexibility only when the money behind them remains coordinated.
A strong line can appear at one book while most of the available cash sits idle at another. Funding a single account heavily makes that mismatch common; dividing funds too evenly creates the opposite problem, with no account holding enough for a normal stake.
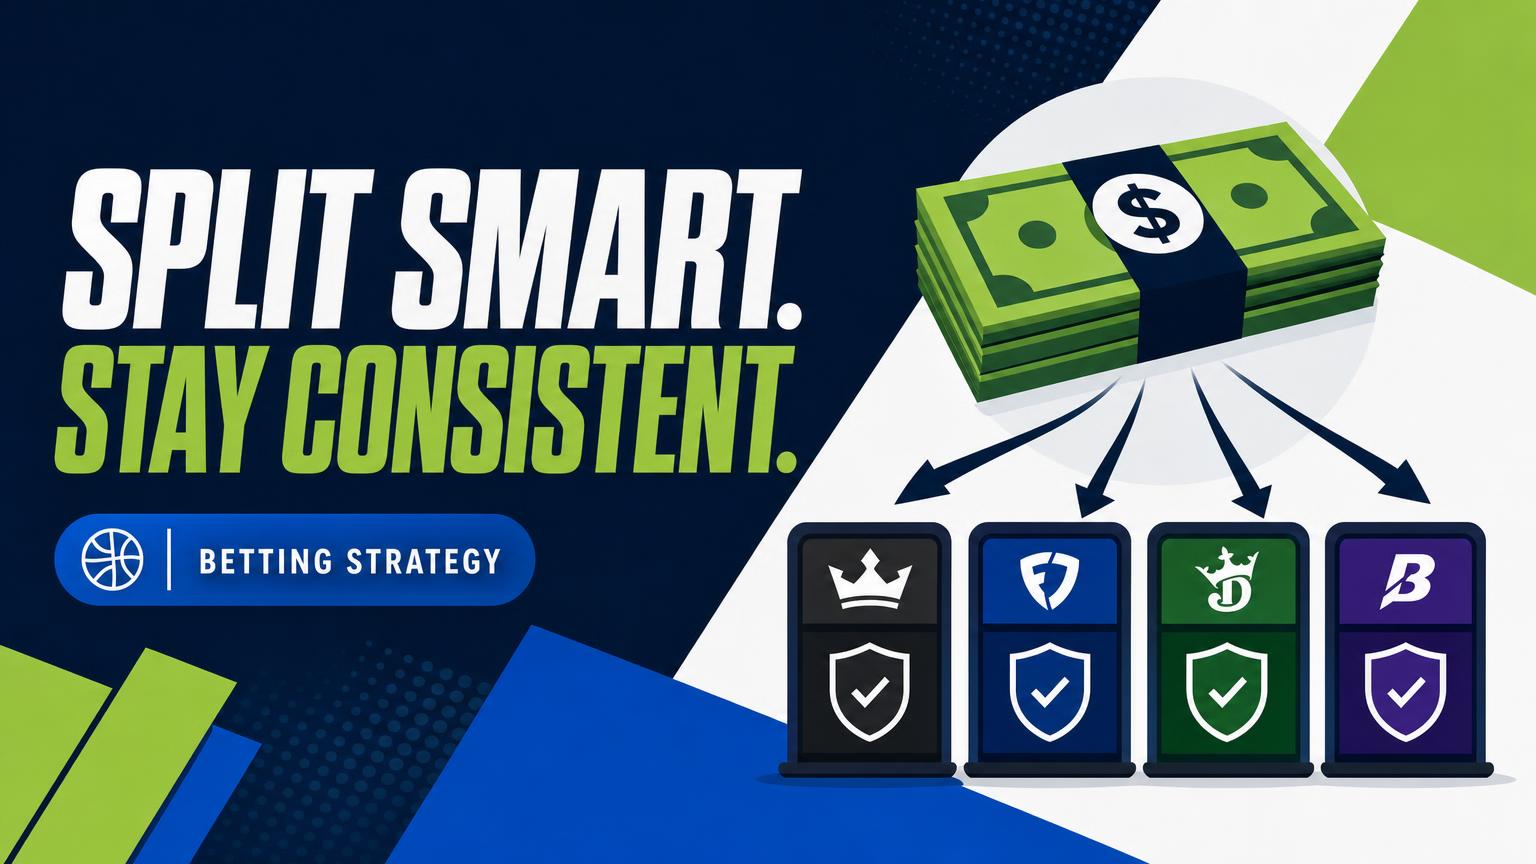
The cleaner approach is to treat every sportsbook balance as part of one consolidated bankroll. A $1,000 bankroll remains $1,000 whether it sits in two accounts or ten. Stakes, deposits, withdrawals, and results should all feed the same ledger. Each book then functions as a place to access prices—not as an independent pot with its own risk tolerance. This keeps overall exposure visible and prevents a winning balance at one book from disguising losses elsewhere.
Set the bankroll before splitting it
The bankroll should contain only disposable cash that could be lost without affecting rent, bills, debt payments, savings goals, or everyday spending. Exclude pending withdrawals until they clear, promotional credits that cannot be withdrawn as cash, and anticipated winnings from unsettled bets. This conservative definition is central to beginner-friendly bankroll management.
Set one unit at roughly 0.5%–2% of the verified bankroll. A $2,000 bankroll therefore gives a unit range of $10–$40; the lower end suits volatile markets or anyone still testing a strategy. Unit size should be recalculated on a fixed schedule—such as monthly—not after every win or loss.
Add firm exposure caps before funding individual sportsbooks:
- Daily cap: maximum total amount risked in one day.
- Weekly cap: a backstop against repeated losing sessions.
- Event cap: the combined risk across all bets tied to one game or outcome.
Exposure means money currently at risk, regardless of which sportsbook holds the bet. A practical starting point might be 3% daily, 8% weekly, and 2% on any single event.
Build a practical sportsbook roster
Start with three to five licensed sportsbooks—enough to compare prices without making recordkeeping cumbersome. Confirm that each operator is legal in the bettor’s location, then assess:
- Line quality: competitive odds on frequently played markets
- Market access: useful leagues, props, and bet types
- Stake acceptance: limits suitable for the planned unit size
- Payments: convenient deposit methods with reasonable processing times
- Withdrawals: clear verification rules and a dependable payout record
Test a new account with modest deposits and withdrawals before assigning it a larger bankroll share. Operator limits may still occur; diversification improves flexibility, not immunity.
Never create duplicate accounts, borrow an identity, falsify details, or mask location. These practices can violate terms, trigger account closure, and put balances at risk.
Review MyBookie Before Adding Funds
After confirming local eligibility, examine the 100% deposit match up to $500 plus $25 chip, including all promotion and rollover terms.
Use a core–secondary–reserve split
A useful starting point is to place 50%–60% at one or two core sportsbooks, 20%–30% across secondary books, and keep 15%–25% off-book in a bank account or other accessible payment source. The reserve supports withdrawals, deposits, and rebalancing without leaving the entire bankroll exposed to sportsbook processing delays.
For a $2,000 bankroll, a workable allocation might look like this:
| Role | Allocation | Example |
|---|---|---|
| Core books | 55% | $1,100 |
| Secondary books | 25% | $500 |
| Off-book reserve | 20% | $400 |
The core amount could be divided $700/$400 if one book consistently offers more suitable markets or accepts most of the action. Secondary balances might be $300/$200, providing access to occasional better prices, promotions, or alternate lines.
Equal $400 splits across five books may look tidy, but they rarely match actual betting patterns. A book handling half the monthly volume needs more funding than one used twice a week. Otherwise, frequent deposits become necessary at the busiest account while money sits idle elsewhere.
Review the split after several weeks of tracked wagers. Reallocate according to actual stake volume, withdrawal speed, and balance usage—not brand preference. This structure improves flexibility, though it cannot guarantee that an operator will not apply limits.
Size each account for actual use
Estimate the working balance
A useful starting estimate is:
Required balance = (average stake × expected open bets) + settlement buffer
Compare that figure with the largest legitimate wager likely to be placed at the book. The account should generally hold at least the larger amount, plus a small margin for odds movement or overlapping bets.
For example, a £25 average stake with eight open bets suggests £200 in routine exposure. If settlement can take a day and another four bets may be placed meanwhile, adding £100–£150 is more practical than funding only the current slips.
Match funding to market speed
Futures and slower markets lock cash for longer, so their balances should be treated as committed capital rather than reusable funds. Avoid loading several books with long-dated positions if that leaves too little for regular activity.
Live betting needs ready liquidity but tighter controls. Keep only the session allocation available, and check daily limits and live-session rules before play; rapid markets make accidental overexposure easier.
Keep bonus value outside the bankroll
A promotion is not spendable cash. Track it in a separate bonus balance until every wagering and withdrawal condition has been satisfied.
MyBookie’s welcome offer illustrates the distinction: a 100% deposit match up to $500, a $25 chip, and possible Bet Back Bonus access may have different rules. Before funding, check:
- customer and location eligibility
- minimum or qualifying deposit requirements
- playthrough and expiration terms
- eligible sports, markets, and odds
- withdrawal restrictions or forfeiture triggers
Only the original cash deposit should enter the bankroll allocation. Promotional value can be recorded separately, then reclassified as cash only after it becomes withdrawable.
A “$500 bonus” should not increase unit size or account capacity. Its practical value depends on how much can realistically be cleared under the current terms.
Check the terms before funding
Review eligibility and bonus conditions before deciding whether the welcome offer fits the planned sportsbook split.
Use one unit value everywhere
- Calculate the base unit
Apply the chosen unit percentage to the total bankroll—not to an individual account. A $5,000 bankroll at 1% produces a $50 unit.
- Enter it in every account record
Record the same $50 value beside each sportsbook in the central tracker. This keeps unit sizing consistent across accounts.
- Set stake multipliers
Define a small range, such as 0.5 units for marginal positions, 1 unit for standard plays, and 1.5 units for stronger measured edges.
- Ignore visible account balances
A well-funded account does not justify a larger wager. Balance determines where a bet can be placed, not how much should be risked.
- Recalculate on a schedule
Update the monetary unit only at a planned review point, such as monthly, rather than after individual wins or losses.
Keep risk anchored to the total bankroll
A well-funded account can make larger bets feel affordable, but its balance is only one slice of the bankroll. The chosen staking method across multiple sportsbooks should govern every wager, regardless of where the money sits.
Before placing a bet, total all unsettled stakes across every book. If the framework allows five units of daily exposure and four units are already open, only one unit remains—even if another account holds plenty of cash.
A loss does not reset that allowance. Switching books to double the next stake is still loss-chasing, merely hidden behind another login. Transfers may restore an account’s operating balance, but they should never enlarge the original risk budget.
Route every wager deliberately
For each planned wager, check three things in order: price, account capacity, and portfolio exposure. First, compare odds across funded, licensed books. Then confirm the selected account can accept the intended stake without exceeding its balance or posted maximum. Finally, verify that total open risk remains below the event, sport, and bankroll caps.
A simple routing log can record:
- Selected book and odds
- Stake requested and accepted
- Exposure after placement
If the best-priced book cannot take the full stake, use the next-best legitimate option or reduce the wager. A slightly worse line is preferable to breaching a risk cap or forcing questionable account activity.
Maintaining several genuine accounts reduces dependence on any one book. Threshold gaming, disguised betting patterns, and replacement accounts after a restriction are not sound workarounds; they may violate terms and create payment or closure risks.
Track, reconcile, and rebalance
A single ledger should treat every sportsbook account as part of one portfolio. For each account, record:
- Transactions: deposits, withdrawals, transfers, fees, and dates
- Balances: withdrawable cash and bonus funds in separate columns
- Open wagers: event, stake, odds, placement date, and potential return
- Settled wagers: win, loss, void, or push, plus net result
- Consolidated value: cash plus stakes tied up in pending wagers, excluding restricted bonus value
Reconcile the ledger against each account weekly. Small discrepancies often come from unsettled bets, voids, fees, or withdrawals still being processed; each should be identified before changing account allocations.
Review the split monthly, but transfer funds only when an imbalance affects normal betting—for example, a frequently used account falls below its operating target while another holds substantial idle cash. A preset trigger, such as 10% of the total bankroll, can prevent needless movement. Delayed withdrawals should remain listed as receivables, and ordinary winning or losing variance should not prompt immediate rebalancing.
Before funding accounts, run the same checklist:
Confirm the total disposable-cash bankroll. Set one percentage-based unit size. Choose licensed, policy-compliant sportsbooks. Assign core, secondary, and reserve allocations. Keep promotional balances separate until withdrawable. Check aggregate open exposure against portfolio caps. Reconcile balances and rebalance on a fixed schedule.Start with only two or three books. Add another only when it provides a specific advantage: better prices, access to a needed market, or backup capacity. For more structured practice, consider courses that explain bankroll distribution. A larger roster without a defined purpose usually adds tracking work rather than useful flexibility.